

CROSS-BORDER ESTATE PLANNING
Your assets are in more than one country. Your estate plan has to work across all of them.
Whether you moved here from the UK and kept a house there, you live overseas and own property in New Zealand, or you are about to inherit from an estate abroad, we plan the New Zealand side and work alongside your advisers in the other country.
WHY THIS MATTERS
A will that works perfectly in one country can be the thing that causes the problem in the other.
Most people with assets in more than one country already have a will. Often they have two: one made here, and one made years ago in the country they came from. Nobody has ever read them side by side.
Each was drafted properly for the country it was made in. The difficulty is what happens between them. Two wills can revoke each other, appoint executors who have no authority to act here, or leave the same asset to two different people. Sometimes neither will reaches the asset the client was most concerned about.
None of this surfaces while you are alive. It surfaces when your family is dealing with two legal systems, two sets of lawyers and two timetables, at the worst possible time.
WHAT GOES WRONG
Your will does not decide which country's law applies. The asset does.
New Zealand law governs who inherits your New Zealand land, whatever your will says and wherever in the world you live. Land overseas is governed by the law of the country it sits in. Your bank accounts, shares and other movable assets follow a third rule again: the law of the country you are legally domiciled in when you die.
Domicile is a technical question and people are frequently wrong about their own. It is not the same as where you live, or where you pay tax, and moving countries does not change it automatically. Someone who left the UK twenty years ago may still be domiciled there.
That split is the source of most cross-border estate problems. A will drafted overseas can deal properly with everything except the New Zealand house. A New Zealand will can say nothing useful about a pension held abroad that was never going to pass under a will in the first place.
WHAT WE LOOK AT
Cross-border estate planning is a review of everything, in every country involved.
Every will you already hold
Wills made in different countries at different times, read against each other. We check whether one revokes another, whether the executors named can actually act here, and whether any asset has been left twice or left out entirely.
Where each asset actually sits
New Zealand land follows New Zealand law. Overseas land follows the law of the country it is in. Accounts, shares and investments follow a different rule again. We list every asset and identify which country's law reaches it.
Your domicile
Where you are legally domiciled at your death determines who inherits your movable assets. We work through it with you properly rather than assuming the answer, because it changes what your documents need to do.
How each asset is owned
Property held jointly can pass automatically to the surviving owner, and your will has no effect on it. Ownership structures differ between countries and the same words can carry different meanings. We check the actual title in each country.
Pensions and superannuation
UK pensions and Australian superannuation usually pass outside your will, under the scheme's own rules or a nomination form you may have signed years ago. If nobody checks the nomination, the money can go somewhere you never intended.
Your relationship
New Zealand relationship property law can reach movable assets held overseas once one partner is domiciled here. On death, a surviving partner has a choice between taking under the will and claiming a relationship property division, and there is a time limit on making it. In a cross-border estate that time limit can be tied to a New Zealand grant that nobody has applied for yet.
Tax in the other country
We identify where a foreign tax is likely to arise and coordinate with a tax adviser in that country if required.
WHO IT'S FOR
You do not need a large estate for this to matter. You need a life in more than one country.
You moved to New Zealand and still own property or accounts overseas
You hold a will made in another country
You have a UK pension or Australian superannuation
You live overseas and own property in New Zealand
You expect to inherit from an estate abroad
You are a beneficiary or trustee of a trust set up in another country
You hold United States shares or property, or you are a US citizen or green card holder
Your partner or children live in a different country from you
You are planning to leave New Zealand, or planning to return
You have been appointed executor of an estate with assets in two countries
HOW IT WORKS
The work is in the sequence. Drafting comes last.
01
Consultation
One hour. We take the detail of what you own and where, and give you our advice on the position. For most clients this is the first time anyone has looked at the whole picture with them.
02
Coordinating overseas advice
If your matter needs advice in another country, we instruct the overseas lawyer or accountant and brief them ourselves, so you are not relaying technical questions between two professionals.
03
Mapping your position
Once any overseas advice is in, we confirm where you stand across every country and tell you what needs to be done.
04
Drafting and signing
We draft the New Zealand documents to sit alongside the foreign ones, and take you through signing. We follow up until it is done.
ISSUES BY COUNTRY
Where our cross-border work comes from, and what tends to come up.
The three countries below account for most of the cross-border work we see. What follows is a general guide to the questions that arise most often, written to help you work out whether any of them might apply to you. We advise on New Zealand law. Where your matter needs advice in one of these countries, we say so, instruct the right adviser there and brief them ourselves, and make sure the New Zealand documents and the foreign ones are drafted to work together.
General information only. It is not advice on the law of any of these countries, and no responsibility is accepted for reliance on it.
United Kingdom
Australia
United States
MOST COMMON
United Kingdom
The largest source of our cross-border work, and the one where the gap between what clients expect and what applies is widest.
New Zealand has no inheritance tax. The UK does, and it can still reach you.
Clients who have lived here for years frequently assume the UK has stopped being relevant. The UK taxes estates by reference to a person's longer-term connection with the UK, and the rules on how that connection is measured were changed recently. Someone who left decades ago can still be within reach. This needs UK advice, and it needs it early, because the answer can change how the New Zealand documents are drafted.
UK pensions almost never pass under a will
The scheme decides, usually guided by a nomination form. We regularly see nominations that still name a former partner, or that were completed before children were born.
UK land stays under UK law
If you own a house or a flat there, your New Zealand will is unlikely to be the right instrument for it. You will usually need a UK document dealing with the UK property, drafted so the two wills work together rather than against each other.
Getting authority to deal with UK assets is a separate process
A New Zealand grant can often be used in the UK, but it is its own application, on its own timetable, running in parallel with the New Zealand one. Building that expectation in early saves your executor a great deal of frustration.
Inheriting from a UK estate while living here
The money arriving in your account is not the end of the matter. How you receive it, whether it goes into a trust, and how it interacts with your own relationship property position are all worth advice before the funds land.
CLOSEST SYSTEM
Australia
The most similar legal system to ours, which is exactly why the differences get missed.
Australian succession law is state based
A will that works in New South Wales is not read the same way in Queensland or Victoria, and the rules on who can claim against an estate differ between states. Which state your Australian assets sit in matters.
Superannuation is the single biggest issue
It usually does not pass under your will. Whether your nomination binds the fund, and whether it is still current, matters more than what the will says about it.
Who you leave Australian assets to can matter as much as what you leave
Australia has no inheritance tax, but it does tax capital gains, and leaving certain Australian assets to a beneficiary who lives outside Australia can trigger a tax bill that would not have arisen if the same asset went to an Australian resident. Worth knowing before the will is drafted, not after.
Administration is comparatively straightforward
Australian grants of probate can generally be recognised by the New Zealand court, which makes trans-Tasman estates easier to administer than most. The planning still needs doing; the process afterwards is kinder.
HIGHEST RISK
United States
The least common of the three, and the one where getting it wrong is most expensive.
US shares are US assets, even held through a New Zealand platform
The United States taxes estates on assets located there. The exemption available to someone who is not American is very much smaller than the one available to a US citizen. Plenty of New Zealanders hold US shares in an ordinary investment portfolio without realising those holdings are exposed.
A US citizen or green card holder living here stays inside the US system
The United States taxes its citizens wherever they live, and its rules treat an ordinary New Zealand family trust as a complicated foreign structure with reporting obligations attached. This is one of the few situations where we will tell a client to get US advice before setting up a trust at all.
US probate cannot be recognised here the way a UK or Australian one can
A US grant is state based and falls outside the recognition process New Zealand applies to Commonwealth grants. A separate New Zealand application is generally needed, which adds time and cost to an estate that is already dealing with two systems.
An American beneficiary brings the US with them
If a child or grandchild is a US citizen, US rules can follow their inheritance even where you have no US connection at all. It is worth knowing before you draft, particularly if you were planning to leave their share in trust.
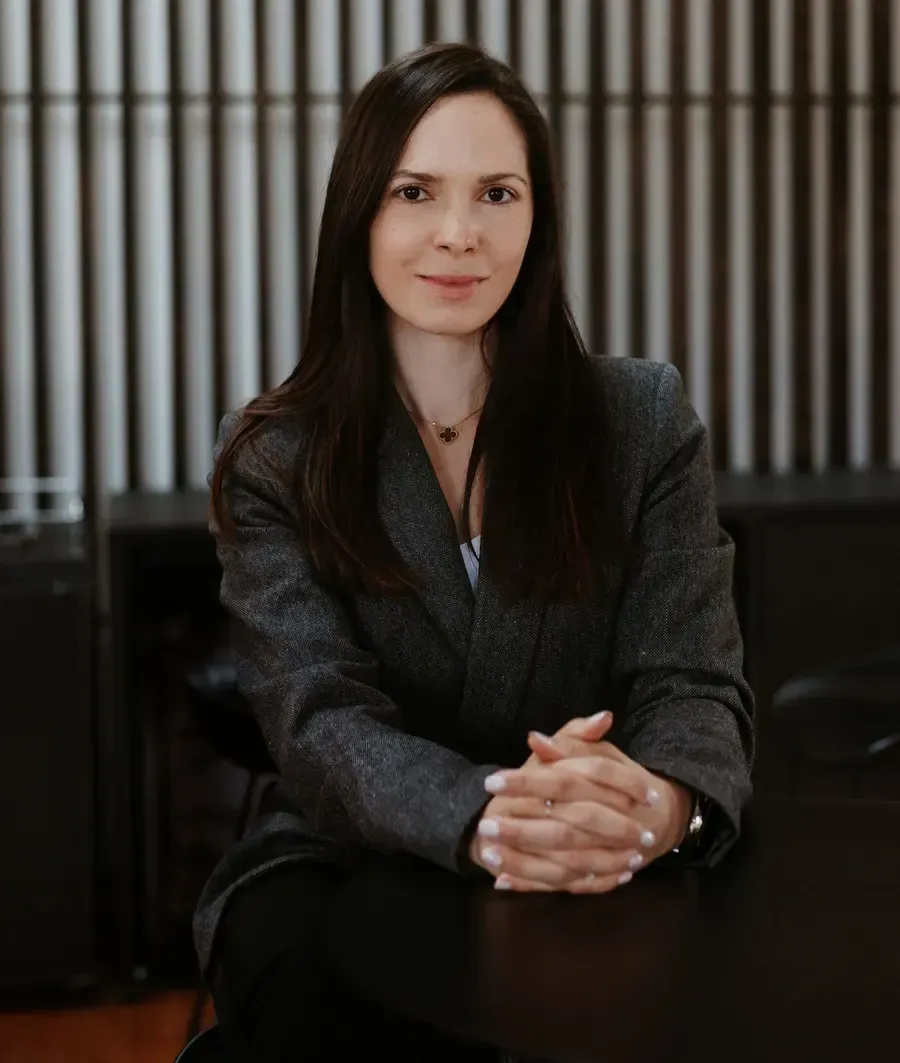
We hold STEP's cross-border qualification.
Polina holds the STEP Advanced Certificate in Cross-Border Estates and the STEP Advanced Diploma in Trusts and Estates, alongside ten years of experience in private client and relationship property law.
"What this means for you"
Knowing which questions the other country is going to raise, and at what point you need someone there rather than here. Getting that judgement right, early, is most of the value in this work, and it is what the qualification trains you to do.
WHAT IS AT STAKE
Two versions of the same estate.
The difference between them is a few hours of work, done while you are here to answer the questions.
Sorted
What you end up with
A written record of everything you own, in which country, and whose law decides who gets it.
Documents in both countries that say the same thing, drafted so neither one cancels the other out.
Pensions, superannuation and jointly owned property checked, with the nominations brought up to date.
Your executor knowing who to contact in each country and in what order, on day one.
An answer, at last, to the question you have been carrying around for a while.
Left as it is
What your family deals with
A second will surfacing after the first has already been acted on, and nobody sure which one governs.
Nobody able to say whether the overseas house is covered, and a bill for finding out.
A pension paid to whoever was named on a form you signed years ago and never looked at again.
New Zealand assets sitting frozen for months while authority is obtained in another country.
Two sets of lawyers, in two time zones, reconstructing decisions you could have made in a single meeting.
WHAT IT COSTS
Fixed fees. Confirmed upfront.
Assets Across Commonwealth from $2,800 + GST individual · $4,500 + GST couple
You may be a New Zealander living overseas holding assets across countries, or a non-New Zealander holding assets in New Zealand. Determination of domicile is required.
Assets include assets located in civil law countries from $4,500 + GST individual · $6,500 + GST couple
This applies to complicated cross-border cases where assets include those in civil law countries and/or uncertain domicile.
Three or more countries, an overriding jurisdiction, or uncertain domicile from $8,500 + GST individual · from $12,500 + GST couple
For three or more countries, a country that overrides your will, or a real question about where you are legally at home. Scoped at your first meeting and then fixed.
Foreign lawyers’ fees are separate.
RESOURCES
Read before you book.
One life, two countries: structuring your will when you hold assets in New Zealand and the UK
Where an asset sits and where you belong, one worldwide will or a will in each country, and the assets that do not pass under your will.
Guides you can download
Five PK Law PDF guides, covering estate planning, KiwiSaver, prenups, contracting out agreements and separation agreements.